
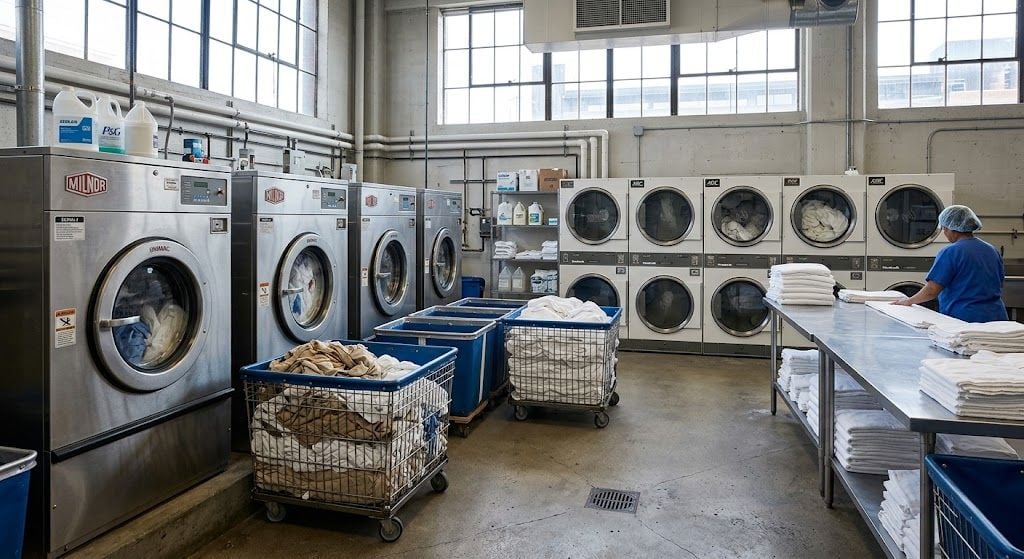
Commercial laundry equipment financing lets a business acquire washer-extractors, industrial dryers, ironers, and related machinery without paying the full purchase price upfront. Because the equipment typically secures the financing, lenders can evaluate the asset alongside your credit profile, cash flow, and operating history rather than requiring unrelated collateral. Terms are usually set against how long the equipment is expected to keep working.
Hotels, linen and uniform services, and property owners running on-premises laundry rooms can use financing to spread the acquisition cost over the equipment’s working life while preserving cash for operations.
What Commercial Laundry Equipment Financing Covers
Equipment financing is funding tied to a specific asset purchase, where the asset secures the loan. In a commercial laundry deal, that means the washers, dryers and finishing equipment on the invoice. With an equipment loan you generally own the machines from purchase, while the lender holds a security interest in them until the loan is paid off. Disbursement varies by transaction, with some lenders paying the distributor directly and others funding the borrower.
Most laundry deals involve some mix of the following:
- Washer-extractors, from small on-premises units to high-capacity machines
- Industrial dryers and tumblers
- Flatwork ironers, feeders and folders for linen operations
- Water heating, steam generation and related support equipment
- Payment and monitoring systems for common-area laundry rooms
The same purchase is sometimes structured as laundry equipment leasing rather than a loan, which changes who holds title during the term and what you owe at the end. Ask which one you are being quoted, because the payments can look similar.
Buying refurbished machines is common here and changes the underwriting. Our guide to equipment financing for used equipment covers how age and condition affect what a lender will approve.
💡 Pro Tip
The smartest funding decisions come from understanding the full cost, not just the monthly amount. Visit our guides for more exclusive tips.
Why Laundry Equipment Suits This Kind of Funding
Two features make lenders comfortable with laundry machinery.
The first is working life. Commercial laundry equipment can have a long useful life, and lenders commonly consider remaining useful life when setting the financing term. A longer term generally means a smaller monthly payment against the same purchase.
The second is resale. These machines have an active secondary market, and distributors move used equipment constantly, which gives a lender a realistic recovery path if a deal goes wrong. Categories with thin resale markets draw harder terms.
The Costs That Sit Outside the Equipment Loan
The machines are one number. Getting them installed and running is another, and the second number catches operators by surprise.
A commercial laundry installation can involve upgraded water and drain lines, gas or steam connections, higher-amperage electrical service, venting, floor reinforcement for extraction loads, and removal of the old machines. Those costs do not always sit inside the equipment invoice a lender is financing.
Some lenders finance freight and installation as soft costs when they appear on the distributor’s invoice. Others finance the hardware only. Ask before you sign, because a $12,000 site preparation bill you assumed was covered becomes a cash expense on delivery day.
If you are pricing out a coin-operated retail location rather than replacing machines in an operating business, our breakdown of what it costs to open a laundromat is the better starting point.
Need Funds Quickly?
What Lenders Weigh on a Laundry Deal
| Factor | Why it matters |
| Time in business and revenue | Shows you can carry the payment from operations, not projections |
| Equipment type and age | Drives the term length and how much of the purchase gets financed |
| Distributor invoice | A clear invoice from an established supplier moves faster |
| Installation scope | Tells the lender how much cash you need outside the loan |
| Credit profile | Can affect eligibility, pricing, down payment and terms |
| Existing liens | May require payoff, subordination, an intercreditor agreement or a carve-out |
When Replacing Beats Repairing
Operators often nurse a failing machine through another season because replacement feels like the expensive choice. Run the numbers first.
Replacing inefficient washers with qualifying certified models can reduce utility use. According to ENERGY STAR, certified commercial clothes washers are on average 9 percent more efficient and use about 45 percent less water than standard models. Across a bank of machines running daily loads, that lands on a utility bill every month. ENERGY STAR also lists utility partners that sponsor rebates on certified equipment.
Imagine an operator running eight aging washers, absorbing rising water costs and a repair bill every few weeks. Financing replacements converts an unpredictable maintenance expense into a fixed monthly payment, which may be partly offset by lower utility use and reduced downtime. Weigh that payment against what the old machines already cost each month, rather than against the purchase price alone.
Finance Commercial Laundry Equipment with Delta Capital Group
Delta Capital Group provides unsecured working capital from $5,000 to $5,000,000 to business owners across the country, along with equipment financing structured around the equipment’s useful life. No collateral required beyond the equipment for most equipment financing. Approvals happen in as little as 24 hours, and 95 percent of approved applicants are funded within 48 hours. Minimum qualifications are 6 months in business, $15,000 in monthly revenue, and a 500 credit score. Apply at deltacapitalgroup.com.
Frequently Asked Questions
Does commercial laundry equipment financing cover installation?
Freight, delivery and installation may be financeable depending on the program. Plumbing, electrical and other site work may or may not qualify, so confirm exactly what the financed amount includes before the equipment ships.
How long are the terms on laundry equipment financing?
Terms are set against the equipment’s expected working life. The exact term depends on whether the machines are new or used, their condition, and the lender’s program. Longer terms lower the monthly payment and raise total interest.
Can you qualify with a 500 credit score?
Delta publishes a 500 FICO minimum alongside six months in business and $15,000 in monthly revenue, subject to underwriting. Your credit profile can still affect approval, pricing, down payment and other terms.
Is the equipment the only collateral required?
Delta states that most equipment-finance transactions do not require collateral beyond the financed equipment, but requirements vary by transaction. A lender may also require a personal guarantee or other protections.
Can you finance laundry equipment in a building you lease?
Generally yes, though the lender may want a landlord waiver confirming it can remove the equipment if the loan defaults. This comes up often with on-premises laundry rooms and hospitality installations. Raise it early, because obtaining the waiver can add time to closing.
How quickly can a laundry equipment deal fund?
Delta says approvals can happen in as little as 24 hours and that approved applicants can fund quickly. An equipment transaction may take longer if the lender is waiting on a final invoice, vendor verification, inspection, insurance or a landlord waiver.

