
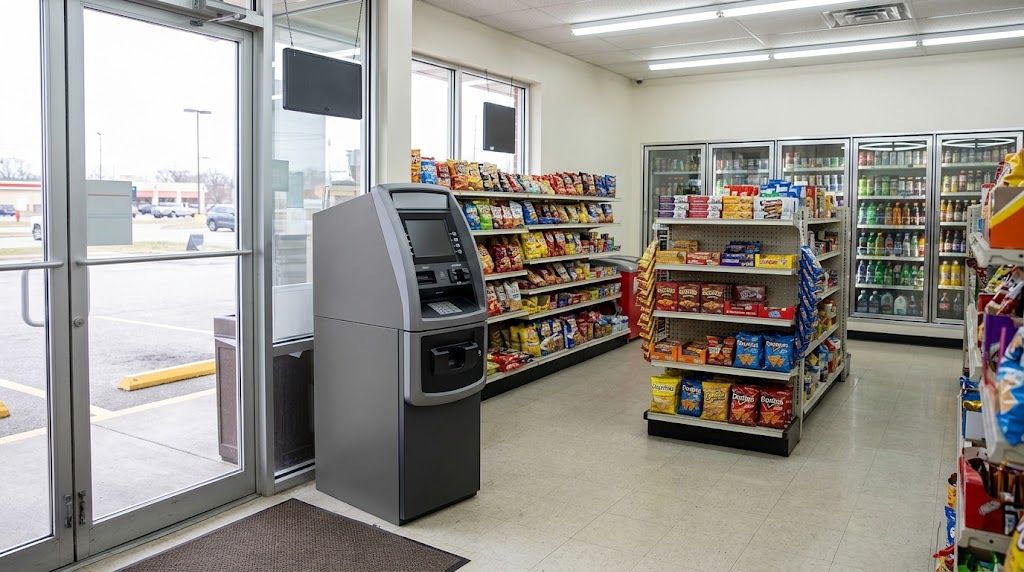
Starting an ATM business runs roughly $4,700 to $22,600 for a single machine, or about $13,100 to $61,800 for a three-machine route, as planning ranges based on the assumptions in the table below. Vault cash, the money you load and keep loaded, can rival or exceed the cost of the machine and becomes a major capital requirement as the route grows.
Before planning the funding: Delta Capital Group’s current minimums are 6 months in business, $15,000 in monthly revenue, and a 500 credit score, so Delta’s products are aimed at businesses that are already operating rather than pre-revenue launches. Because Delta requires six months in business, a new ATM operator would need to use personal capital or another startup-funding source until the business meets Delta’s eligibility requirements.
The Cost Breakdown
| Category | Per machine | Three-machine route |
| ATM unit, new | $2,000 to $8,000 | $6,000 to $24,000 |
| Installation, signage and connectivity | $200 to $1,000 | $600 to $3,000 |
| Vault cash loaded in the machine | $2,000 to $10,000 | $6,000 to $30,000 |
| Business registration, insurance, compliance | included below | $500 to $3,000 |
| Monitoring and processing software, first year | $0 to $600 | $0 to $1,800 |
| Total | $4,700 to $22,600 | $13,100 to $61,800 |
Used machines start lower, often from around $1,500, and are common for a first placement. The trade-off is shorter remaining service life and less certainty about compliance with current standards.
Vault Cash Is the Real Commitment
If you self-fund the ATM’s vault cash, that money remains your capital while it sits in the machine, and third-party vault-cash programs are an alternative. A machine dispensing $20 notes into a busy location may need $5,000 to $10,000 loaded to avoid running dry over a weekend. That money is not spent, but it is not available either.
This is the part that determines how fast you can add machines. Each placement requires additional vault cash in circulation. As customers withdraw cash, the withdrawal amounts are returned through the settlement process, while the operator must keep enough cash deployed to cover activity between reloads. The practical constraint on growth is often how much cash you can keep deployed rather than machine cost.
Cash is also the operational burden. Somebody has to count it, load it, reconcile it, and carry the risk of doing so. Armored carrier service can outsource much of the physical cash handling, but it adds a recurring cost and does not eliminate reconciliation or oversight.
Placement Decides Whether the Machine Earns
ATM revenue commonly comes from the cardholder surcharge plus net interchange, while location determines transaction volume. Bars, nightclubs, convenience stores, laundromats, event venues, and cash-preferred restaurants perform because customers need cash on the spot.
Expect to negotiate with the site owner. Some placements are free in exchange for the convenience to customers. Others require a share of the surcharge or a flat monthly rent. A revenue share on a busy site usually beats a free placement on a quiet one.
Test the assumption before signing anything. Ask the site owner how many customers ask for cash or get turned away at the register, and watch the location at its busiest hour.
Cash Use Is Not Disappearing
The common objection to this business is that cash is dying. The data does not support that reading.
According to the Federal Reserve’s 2026 Diary of Consumer Payment Choice, 76 percent of consumers carried cash in their pocket, purse, or wallet in 2025, holding an average of $69. Nearly half, 45 percent, stored an average of $364 in cash elsewhere for savings or emergencies. Four out of five consumers used cash in the last 30 days, and 90 percent plan to continue using it.
Cash has declined as a share of total payments while remaining a stable presence in everyday spending. For a route operator, what matters is that enough people still want notes in specific places at specific times.
Compliance and Registration
A standard independent ATM operator that only gives customers access to their existing bank accounts for withdrawals and balance inquiries generally is not treated as a money services business merely because it operates the ATM. Your processor and sponsoring bank will still perform Bank Secrecy Act and customer due diligence checks, and state, local, network, and accessibility requirements may apply. An operator offering additional money-transmission services can face different rules.
Treat this as part of the setup rather than an afterthought. Confirming your obligations with your processor before the first placement is far cheaper than correcting them later.
Funding a Growing Route
Two costs recur as a route expands: machines and vault cash. They suit different products. ATM machines may qualify for equipment financing, particularly in a multi-unit purchase, subject to lender minimums and underwriting. Vault cash generally requires separate working-capital funding because it is not part of the ATM equipment purchase. A working capital loan or a line of credit fits that need better.
Operators adding several placements at once may use both together. Our guide to business expansion loans covers structuring growth capital across a route build-out.
| Feature | Unsecured | Secured |
|---|---|---|
| Collateral | None | Required |
| Approval Speed | 24-48 hrs | 2-4 weeks |
| Credit Score | 500+ | 650+ |
Fund Your ATM Route with Delta Capital Group
Delta Capital Group provides unsecured working capital from $5,000 to $5,000,000 to business owners across the country, along with equipment financing structured around the equipment’s useful life. No collateral required beyond the equipment for most equipment financing. Approvals happen in as little as 24 hours, and 95 percent of approved applicants are funded within 48 hours. Minimum qualifications are 6 months in business, $15,000 in monthly revenue, and a 500 credit score. Apply at deltacapitalgroup.com.
Frequently Asked Questions
How much does a single ATM machine cost?
New units commonly run $2,000 to $8,000 depending on capabilities and whether it is a through-the-wall or freestanding model. Used machines start lower, often around $1,500. Installation, signage and connectivity add a few hundred dollars more.
How much cash do I need to load in an ATM?
Enough to last between visits. A quiet location may hold $2,000, while a busy bar or venue can need $10,000 to get through a weekend. Running empty costs you the transactions and annoys the site owner.
Do I need a license to run an ATM business?
Requirements depend on your state, your structure, and the services you offer. Standard withdrawal and balance-inquiry operations are generally not treated as money services business activity on its own, but state, local, and network rules may still apply, and your processor and its sponsoring bank will impose their own standards. Confirm before placing your first machine.
Can I finance the ATM machines?
The machines may be eligible for equipment financing, particularly in a multi-unit purchase, subject to lender minimums and underwriting. Vault cash generally requires separate working-capital funding because it is not part of the ATM equipment purchase.
Who fills the machine with cash?
Some small operators self-load their machines, while others use vault-cash or armored-service providers. Self-loading keeps costs down and takes time, while third-party service adds a recurring expense that can become worthwhile as the route grows.

